
The financial system may be evolving rapidly, but for many institutions, the path from intention to execution remains unclear.
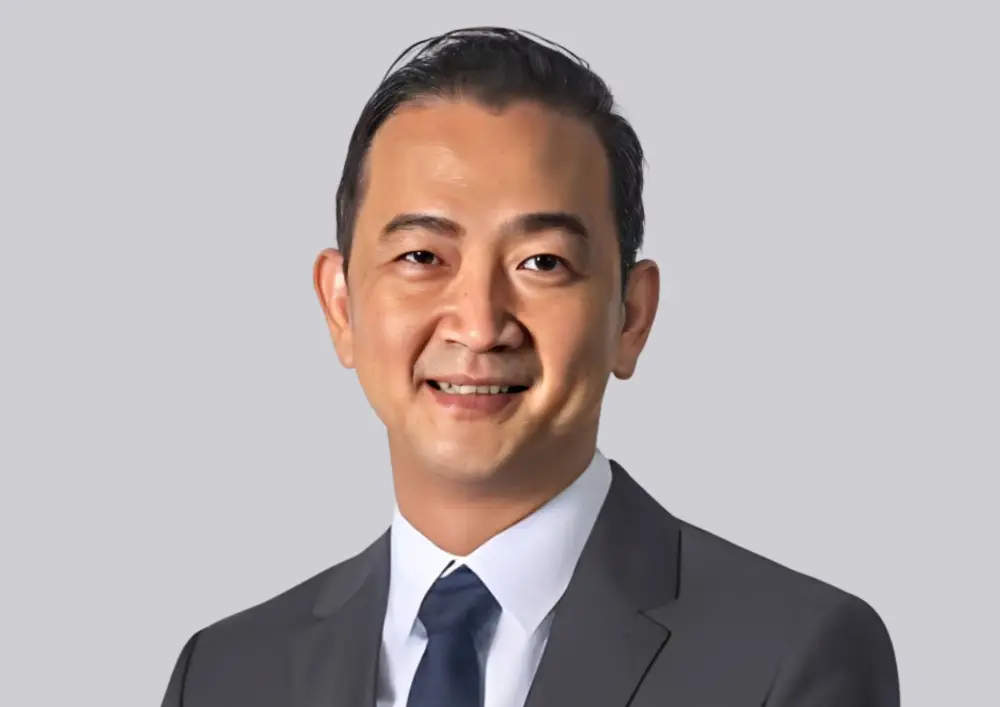
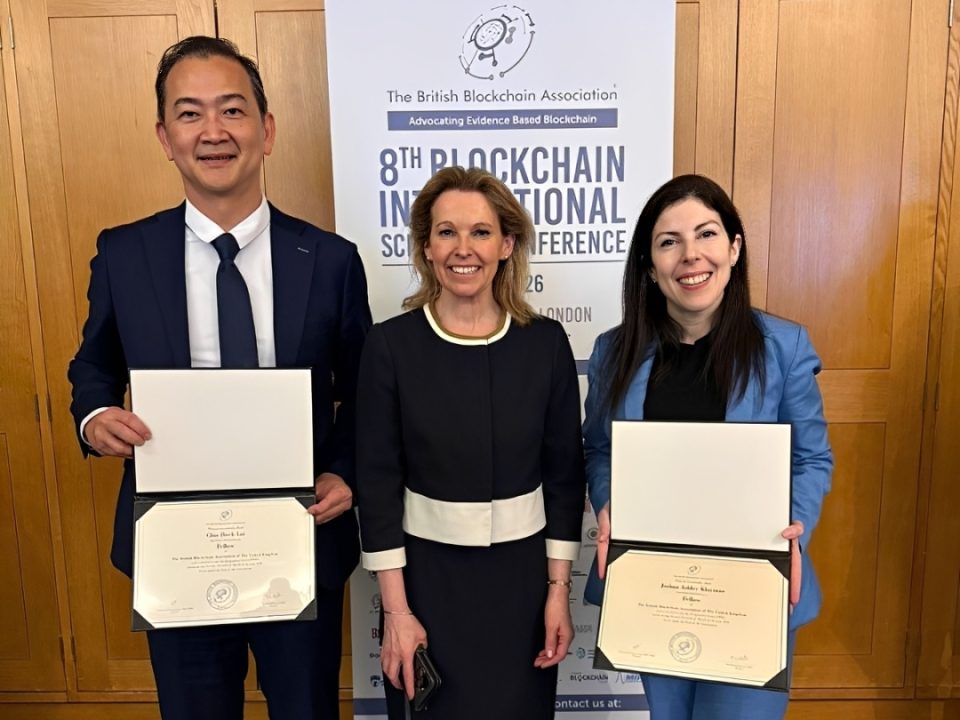
Chia Hock Lai, Co-Founder & CEO (Asia) of Embed Financial Group Holdings, has spent the last decade working at the intersection of digital assets, regulation, and institutional infrastructure. His work focuses on a critical challenge: how to turn fragmented regulatory environments, legacy systems, and cautious institutions into scalable, working financial infrastructure.
In this conversation, he unpacks where most institutions get stuck — and what it will take to move from experimentation to real adoption.
Highlights
The Gap Between Intent and Execution
Q: You’ve said that “the financial system is being rebuilt,” yet many institutions are still hesitant. From your work at Embed Financial Group Holdings, what’s the biggest gap between intent and execution when it comes to digital-asset adoption in Asia?
A: The biggest hurdle isn’t a lack of interest — it’s a legacy-mindset bottleneck.
Too often, institutions treat digital assets as siloed products, essentially trying to force a 21st-century Ferrari into a 19th-century horse-carriage workflow.
At EFGH, we see strong intent to innovate, but execution often breaks down because internal risk frameworks are still built for T+2 settlement cycles and manual oversight.
The real bridge to production is what we call “compliance by design.”
Instead of checking compliance after a trade, we embed it directly into the asset’s DNA.
A good example is ABN AMRO’s €5 million digital green bond. Using the ERC-3643 standard, compliance logic sits on-chain — the bond effectively “knows” its own rules. It will only transfer if the buyer’s digital identity is verified by an authorised registry.
To move from proof-of-concept to scale, institutions need to stop wrapping old processes around new technology — and start embedding compliance at the ledger layer.
Scaling Across Fragmented Markets
Q: Operating across fragmented regulatory environments in Asia is no small feat. How do you approach building digital-asset infrastructure that is both scalable and compliant across multiple jurisdictions?
A: The common assumption is that scalability requires regulatory uniformity. We take a different view.
Scalability comes from connectivity, not uniformity.
We don’t need every country to have identical rules — we need systems that can talk to each other.
That’s where the “Trust Anchor” model comes in, which underpins initiatives like Project Guardian by the Monetary Authority of Singapore.
Think of it as a digital trust stamp.
When a regulated institution in one jurisdiction verifies a client and issues a credential, another compliant system can recognise that verification without repeating the entire KYC process. The authority remains local — what travels is the attestation, not the underlying data.
A similar principle is seen in Project Dunbar, where multiple central banks created a shared technical layer without harmonising their legal systems.
At EFGH, this is the direction we build toward: jurisdiction-aware infrastructure — where compliance is embedded locally, but assets and credentials move seamlessly across borders.
What “Responsible Innovation” Actually Means
Q: Through your roles with the Responsible Fintech Institute and Digital Assets Association, you’re shaping industry standards. What does “responsible innovation” practically look like when deploying digital assets at an institutional level?
A: At the institutional level, responsible innovation means prioritising verifiability over “trustless” narratives.
Legal accountability cannot be abstracted away by code.
In practice, this translates to what we call asset-backed integrity.
Every digital token must have a legally enforceable and auditable link to a real-world asset. Whether it’s a tokenised fund, a green bond, or a regulated stablecoin, responsibility is demonstrated through structured, third-party verified processes — not marketing claims.
A strong benchmark is how Paxos manages its USDP stablecoin, with monthly independent attestations and regulatory oversight.
For institutional-grade digital assets, we require:
- A legal opinion on asset enforceability
- A defined audit cadence
- A clear redemption mechanism
The goal is simple: the math can be transparent, but accountability must be absolute.
Where Tokenisation Is Already Working — And Where It’s Not
Q: Tokenisation of real-world assets (RWA) is gaining momentum — where are you seeing the most viable use cases today, and what still needs to be solved before it reaches mainstream adoption?
A: Tokenisation is already delivering real results in two areas: treasury bills and commodities.
We’re moving assets like bonds and gold onto the ledger not for the sake of innovation, but to remove intermediaries and compress settlement from days to minutes.
The proof is already live.
BlackRock’s BUIDL fund — a tokenised money market fund — has grown to approximately $2.5 billion in market cap and is now tradable on decentralised platforms. This is no longer experimental — it’s a production-scale deployment.
The harder frontier is non-homogeneous assets like real estate and private credit.
Here, the challenge isn’t issuance — it’s secondary market liquidity.
And liquidity is fundamentally a data problem.
The gap between what a local asset owner knows and what a global investor can verify creates information asymmetry, which traps capital.
The real unlock is data standardisation.
Frameworks like ACTUS provide machine-readable models for financial contracts across jurisdictions. That’s what allows a private credit asset in Manila to be evaluated alongside a bond in New York.
Legal structures open the door — but standardised data is what allows capital to flow at scale.
Preparing for the Age of Agentic Finance
Q: As embedded finance and digital assets converge, what capabilities should today’s financial institutions start building now to remain competitive over the next 3–5 years?
A: We are moving toward a world of agentic commerce, where AI agents don’t just recommend decisions — they execute them.
The institutions that stay competitive will be those that build infrastructure not just for humans, but for autonomous agents as counterparties.
The use cases are already emerging.
An AI agent managing a logistics fleet could detect a shipment delay, trigger an insurance claim, and receive a stablecoin payout to reroute cargo — all without human intervention.
The building blocks already exist.
So what should institutions focus on?
First, programmable wallet infrastructure — wallets that can be permissioned, controlled, and audited for AI agents.
Second, identity and credentialing layers for non-human actors. Today’s KYC systems are built for people, not machines.
Third, API-first, event-driven banking infrastructure that can operate at machine speed, rather than human-driven batch cycles.
The institutions that invest in these capabilities will become the orchestrators of the next financial system.
Those that don’t risk being disintermediated — not by competitors, but by protocols.
One critical question remains unresolved: who holds liability when an AI agent makes a mistake?
The frameworks for trust and accountability in agentic finance are still being written.
And the institutions that help shape those standards will hold a lasting advantage.
Final Thoughts: The Institutions That Build Will Win — The Rest Will Watch
Digital assets are no longer experimental. The technology works. The use cases are live. Capital is already moving.
What’s holding institutions back isn’t capability — it’s architecture.
Legacy systems, fragmented compliance frameworks, and hesitation around accountability are creating a widening gap between those who are building real infrastructure and those still stuck in pilot mode.
The next phase of finance will not be defined by who understood the trend earliest.
It will be defined by those who rebuilt their systems fast enough to participate in it.
Because as digital assets, embedded finance, and AI converge, the competitive battlefield is shifting — from products to infrastructure, from transactions to ecosystems, and from human-driven workflows to machine-executed economies.
And in that shift, institutions will not be disrupted by faster competitors.
They will be bypassed entirely.
Highlights
Read the Chinese article here.
Related posts:
 Singapore’s Science + China’s Scale: Why APAC Biotech Winners Must Think Cross-border Early
 From 41 to 111 Startups — She’s Asking Why Southeast Asia’s Femtech Boom Still Isn’t Enough
 Why a Global Impact Leader Believes Southeast Asia Could Produce the Next Social Unicorns
 The AI Race Has Changed: GITEX AI Asia 2026 Signals the End of Model Wars